It's not the most comfortable financial topic.
But it's an important one.
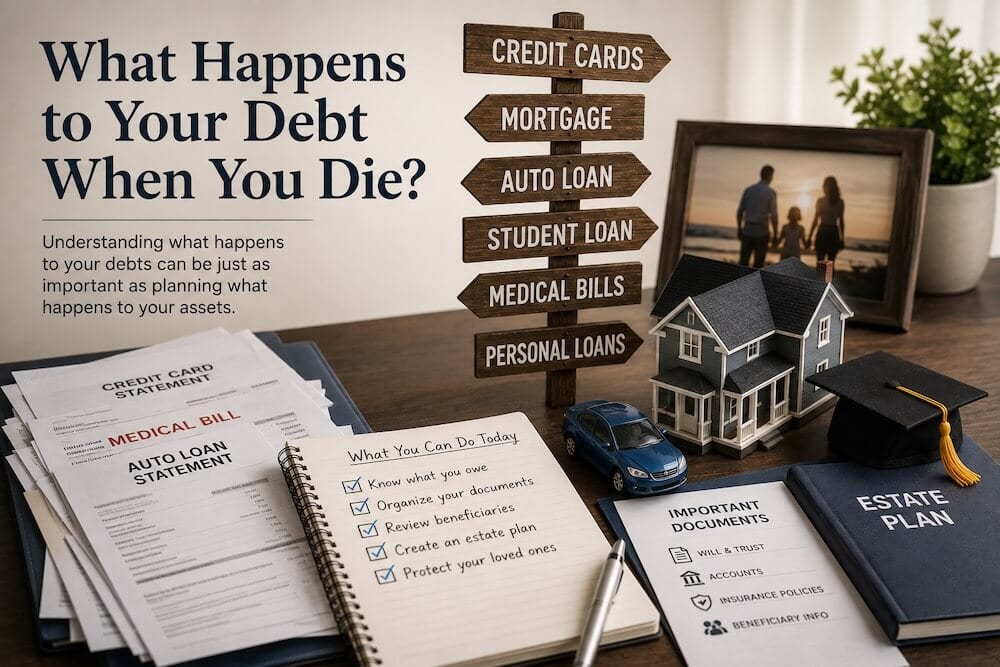
What happens to your debt when you die?
Does the credit card company simply erase the balance? Does your mortgage disappear? Do your children inherit your car loan? Does your spouse suddenly become responsible for everything?
The simple answer is...
Your debt doesn't automatically disappear when you die. But it doesn't automatically become your family's debt either.
Generally, your debts are handled through your estate... And understanding how that works is part of responsible financial planning. |
 |
 |
Your Estate Gets The Bill |
When someone dies, the money and property they leave behind generally become part of their estate.
In many situations, the unpaid debt simply goes unpaid.
Your children generally don't receive a bill simply because they're your children.
Your parents don't automatically become responsible either.
But there are important exceptions.
Your family generally doesn't inherit your individual debt. Your estate may still have to deal with it. |
 |
Different Debts Can Have Different Outcomes |
Credit cards
If your spouse or child is merely an authorized user, that alone generally doesn't make them responsible for paying your balance.
Death doesn't make the mortgage disappear.
The important point is... A $400,000 house with a $250,000 mortgage isn't the same as leaving someone a $400,000 asset free and clear.
Your car loan
The same basic idea applies to a financed vehicle.
But the lender still has an interest in it until the loan is satisfied.
Student loans
Federal student loans have special rules and generally can be discharged after the borrower's death once acceptable documentation is provided.
Private student loans can be different.
Joint and co-signed debt
This is where things change significantly.
They agreed to repay the debt.
Likewise, joint borrowers can remain responsible for shared debts.
You're accepting financial responsibility for the loan. |
 |
Being Family Doesn't Automatically Make The Debt Yours |
Imagine your father passes away with a $12,000 credit card balance.
You may immediately think... "I guess somebody has to pay this."
Maybe.
But that doesn't necessarily mean you have to pay it with your money.
Debt collectors can contact certain people about debts belonging to someone who died.
That doesn't automatically make those people personally responsible.
The CFPB specifically warns survivors not to assume they have to pay a deceased person's debt.
There are exceptions, including certain shared debts and situations where state law creates responsibility.
Never pay a deceased relative's debt from your own money simply because someone tells you that you should. First determine whether you're actually legally responsible. |
 |
Leave Your Family Information, Not Confusion |
This article isn't really about death... It's about preparation.
Think about what someone would have to figure out if you weren't here tomorrow.
Would they know...
You don't necessarily need some elaborate system.
Create a financial inventory and make sure the appropriate person knows how to access the information when necessary...
...And periodically review your beneficiary designations and estate documents.
Don't have a will yet?
If creating or updating your will has been sitting on your to-do list, LegalWills provides an online option for creating a will and other estate-planning documents. [Learn more about LegalWills]
Your family will already have enough to deal with.
|
When people think about leaving something behind, they usually think about assets.
But there's another side of the balance sheet.
Debt.
Part of financial wellness is understanding both sides.
Organize your finances... Know what you owe... Know who is legally connected to those debts... Keep your beneficiaries updated... And make sure someone you trust knows where to find the information they'll need.
Your family generally doesn't inherit your individual debt simply because they're your family.
Until next week,
Disclaimer: Guide to Perfect Credit and Credit Coach Rob provide financial education and coaching based on personal experience and research. We are not licensed financial advisors, accountants or attorneys. This content is for informational purposes only and should not be considered financial, legal or tax advice. Always consult with a certified professional for your specific situation. |
Get The 850 Pin! |
It’s more than a number... it’s a symbol of the journey. My journey started with free t-shirts and ended at 850.
What's yours?
#850Journey #CreditComeback #YouGotThis |