Cancel it or downgrade it
|Subscribe·Archives·Current Issue
Cancel it or downgrade it
Many people cancel cards when a downgrade might be the smarter move.
Credit Coach Rob

Credit Coach Rob

Jun 12, 2026

It happens every year.


You see the charge hit your account and immediately ask yourself...
"Am I really getting my money's worth?"


Maybe you signed up for travel perks, airport lounge access, bonus rewards, elite status benefits...


And maybe those benefits made sense at the time.


But life changes.
Travel slows down.
Spending habits shift.
Priorities evolve.


Now you're looking at that annual fee wondering if it's worth keeping the card at all.


Before you close it, there might be a better option.


Have you ever kept a subscription or service longer than you should have simply because it felt easier than making a change?

Why Closing A Card Is Not Always The Right Move

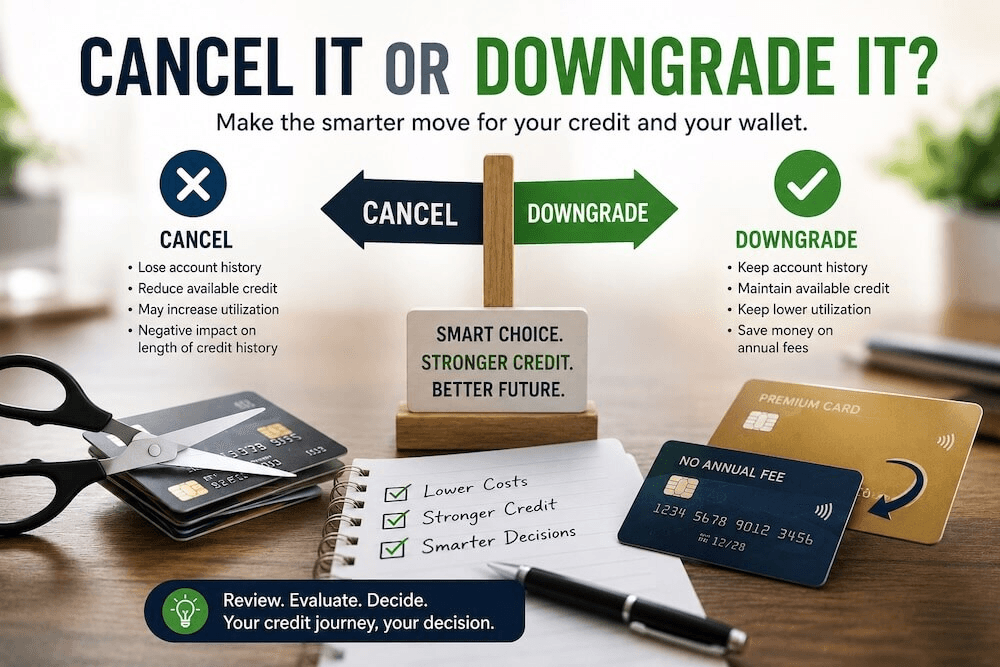
Many people assume there are only two choices... keep the card or cancel the card


But there is often a third option... Downgrading.


A downgrade typically allows you to move from a premium card to a lower-tier version offered by the same issuer.


For example:
premium rewards card → no annual fee version
travel card → basic rewards card


This can help preserve...
account age
available credit
payment history


All of which can contribute to a healthier credit profile.


Sometimes the smartest move is not getting rid of the account. It is making the account fit your current life.

Advertisement
Advertisement

When Downgrading Makes Sense

1. The annual fee no longer makes sense
Ask yourself...
Would I willingly pay this fee today if I did not already own the card?
If the answer is no, it is worth exploring alternatives.


Especially if you rarely use the perks, your spending habits have changed or the rewards no longer justify the cost


2. You want to preserve account history
Older accounts help strengthen your profile over time.


Closing an account may not hurt immediately, but preserving a long-standing account is often beneficial.


Downgrading allows you to keep the relationship, the history and reduce the cost.


3. The card represents a large portion of your available credit
Let's say...
Card limit: $15,000
Total available credit: $25,000


Closing that account could significantly increase your utilization percentage.


Downgrading often allows you to keep the limit while eliminating the fee.


4. You're simplifying your finances
Many people accumulate cards during different stages of life.


Eventually, they realize...
"I don't need six different rewards strategies."


Downgrading can simplify things without sacrificing credit history.


5. You still want access to the issuer
Keeping a downgraded card can preserve...

    • account relationships
    • future upgrade opportunities
    • existing credit limits


Without paying for benefits you no longer use.


Which credit card in your wallet would you question most if the annual fee hit tomorrow?

Stop Paying For Your Old Identity

Sometimes we keep financial products because of who we used to be.


The frequent traveler.
The rewards optimizer.
The business road warrior.
The points collector.


But if your life has changed, your financial tools should change too.


Many people keep paying for premium cards because it feels prestigious, they've had it for years, they don't want to admit they no longer need it


That's not strategy... That's habit.


Financial maturity means regularly asking whether today's expenses still support today's goals.


What financial product are you holding onto because of your past rather than your future?

Advertisement
Advertisement

Before You Downgrade Review These Items

Check the annual fee

    • How much are you paying?
    • What benefits are you actually using?


Review your credit limit

    • Will the limit transfer to the new card?
    • Will available credit remain intact?


Ask about product changes
Call the issuer and ask...

      • What downgrade options exist?
      • Will rewards be affected?
      • Will account history remain unchanged?


Review reward balances
Some programs require you to...use rewards, transfer rewards and/or redeem points before changing products.


Compare alternatives
Make sure the downgraded card actually fits your current needs.

One of the biggest lessons in personal finance is learning that not every decision is forever.


You are allowed to evolve.
Your goals change.
Your spending changes.
Your lifestyle changes.
Your credit cards should change too.


If a premium card still delivers value, keep it.
If it doesn't, do not automatically cancel it.


Explore whether a downgrade helps you keep the benefits that matter while eliminating costs that no longer do.


Because the goal is not collecting cards.
The goal is building a financial life that works for you.

Do you currently have a card you are considering downgrading or closing?


Until next week,


Disclaimer: Guide to Perfect Credit and Credit Coach Rob provide financial education and coaching based on personal experience and research. We are not licensed financial advisors, accountants or attorneys. This content is for informational purposes only and should not be considered financial, legal or tax advice. Always consult with a certified professional for your specific situation.

Get The 850 Pin!

It’s more than a number... it’s a symbol of the journey.

My journey started with free t-shirts and ended at 850.


What's yours?


👉 Check out the 850 Pin


#850Journey #CreditComeback #YouGotThis

This publication sponsored by