Keep more money and raise your score
|Subscribe·Archives·Current Issue
Keep more money and raise your score
You do not need to choose between saving and credit progress. Use this order of operations and let your score follow.
Credit Coach Rob

Credit Coach Rob

Mar 20, 2026

You have probably heard the saying that wealth is measured by how much you keep.


That hits different when you are also trying to improve your credit.


Because improving credit can feel like it requires spending money, paying balances down fast or even paying interest just to “build history.”


But the truth is this.


The same habits that help you keep more money are the habits that raise your score.


Not flashy hacks. Not hustle. Just a clean system.


What is your bigger stress right now. Keeping more money or getting your score up?

Credit rewards stability not sacrifice

Credit scores respond to predictable behaviors.


The big drivers are simple...


    • paying on time
    • keeping balances low relative to limits
    • avoiding too many new accounts at once
    • letting your accounts age


None of that requires you to pay interest.
It requires you to avoid mistakes that create fees, late payments and revolving debt.


When you “keep more” money you are usually doing these things...

    • planning ahead
    • protecting your cash flow
    • avoiding high interest traps
    • being intentional with spending


Those behaviors also protect credit.

Advertisement
Advertisement

The Keep More Order of Operations

Here is the system. Use it in this order...


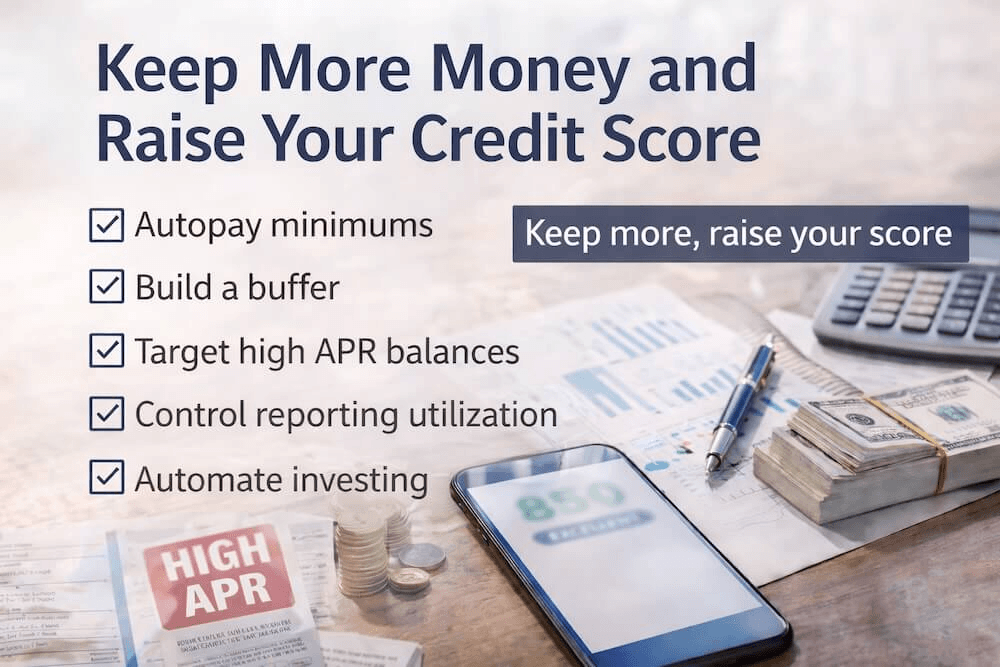
1) Lock payment history first
Your number one job is never missing a payment.


Do this today...

    • set autopay for minimum payments on every credit account
    • set a reminder 7 days before due dates to check balances


Payment history is the foundation. Everything else is optional compared to this.


2) Build a buffer so credit is never your emergency plan
A buffer is what lets you keep more money long term.


Start with a simple target... one paycheck buffer then build toward one month of expenses


When you have a buffer you stop using cards to survive surprise expenses and that protects your utilization and your stress level.


3) Attack high APR balances with precision
If you are carrying debt, “keeping more” money means stopping interest.


Pick one target...the highest APR card first


Then pay extra on that one while paying minimums on the rest.


This increases cash flow over time and it improves utilization as balances drop.


4) Control what reports on your statement
Your score reacts to what gets reported, not what you intend to pay later.


Two simple rules...

    • keep total utilization under 30 percent while rebuilding
    • under 10 percent when you want it to look excellent


If you have a big month, pay the card down before the statement closes so a high balance does not report.


5) Keep new credit boring for a season
When you are stabilizing, reduce new applications.
Hard inquiries and new accounts can temporarily drop scores and they increase risk of overextending.


Let your clean habits do the work.


What step are you missing most right now. Autopay, buffer, payoff, reporting timing, or new credit discipline?

Your score rises when life gets easier to manage

People think the credit journey is about being perfect.


It is not.


It is about reducing the number of moments where you might slip.
Late payments usually happen when life is busy and money is tight.
High balances usually happen when spending is emotional or unplanned.


So the real win is building a system that makes good behavior the default.


You keep more money when you remove leaks.
You build better credit when you remove risk.


Same mission.


The goal is not to impress the credit system. The goal is to become unshakeable when life gets expensive.


Where do you leak money most right now. Eating out, subscriptions, impulse buys, or unexpected expenses?

Advertisement
Advertisement

Make it automatic so it actually sticks

Autopay minimums - the simplest credit protection you can set


One buffer account - separate from checking so you do not accidentally spend it


Statement close tracker - note statement dates for your top cards


One card focus - one payoff target at a time if you carry balances


Spending audit - one 10 minute review weekly, find one leak and plug it

If you want better credit, stop treating it like a separate world.


The habits that build wealth also build trust with the credit system.


Pay on time. Protect your buffer. Stop the interest. Keep what reports clean.


Then let time do what time does.


Until next week,


Disclaimer: Guide to Perfect Credit and Credit Coach Rob provide financial education and coaching based on personal experience and research. We are not licensed financial advisors, accountants or attorneys. This content is for informational purposes only and should not be considered financial, legal or tax advice. Always consult with a certified professional for your specific situation.

Get The 850 Pin!

It’s more than a number... it’s a symbol of the journey.

My journey started with free t-shirts and ended at 850.


What's yours?


👉 Check out the 850 Pin


#850Journey #CreditComeback #YouGotThis

This publication sponsored by