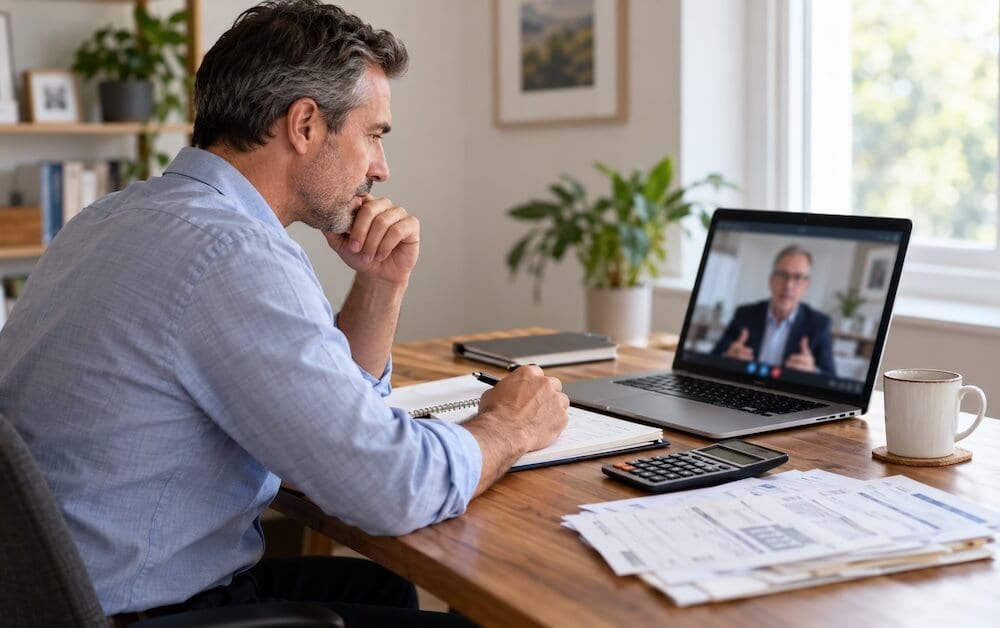
You finally get the email.
Annual review completed.
Salary adjustment approved.
Maybe it's 2%, 3% or even 4%.
You think... "Nice. I got a raise."
And technically, you did.
But then you go grocery shopping. Insurance costs more. Dinner costs more. Utilities cost more.
The things your paycheck needs to buy have gotten more expensive too.
So here's the question I want you to ask... Did you actually get a raise or did your paycheck simply get adjusted while your cost of living moved right along with it?
That's where inflation matters.
A raise tells you how much more you're earning.
Inflation helps tell you how much of that increase you can actually feel.
When was the last time you compared your raise with how much your cost of living had increased? |
 |
 |
There Are 2 Kinds of Raises |
Let's keep this simple.
Your nominal raise is the number your employer gives you. If you make $75,000 and receive a 3% raise, your new salary becomes $77,250
That's an additional $2,250 in gross annual income.
Sounds good.
But there's another number that matters...
Your real raise considers what happened to prices during the same period.
If your salary increased 3% while your cost of living also increased around 3%...
You may have more dollars... But those dollars don't necessarily buy much more.
And if prices rose faster than your salary?
Your purchasing power may have actually declined.
Don't measure financial progress only by how much more you're earning. Measure what that income can actually buy. |
 |
Put Your Raise Through The Inflation Test |
Let's look at a few simple examples.
You received a 2% raise
If prices around you increased roughly 3%... Your paycheck increased. But your purchasing power didn't keep up.
You're earning more on paper while potentially feeling more financial pressure.
You received a 4% raise
If inflation was around 3%... Now you're slightly ahead. But a 4% raise doesn't necessarily mean your financial position improved by the full 4%.
Part of that increase simply helped absorb higher prices.
You received an 8% raise
Now there may be a meaningful gap between your income growth and inflation.
That's where you may begin to feel additional breathing room. Especially if you resist immediately increasing your lifestyle.
What if you didn't receive a raise at all?
This is the part we don't talk about enough.
If your pay remains exactly the same while the things you buy become more expensive...
Your purchasing power is declining. Your salary didn't go down. But what your salary can provide did.
That's effectively a financial step backward.
Look beyond the percentage
Before deciding whether your compensation actually improved, consider salary, bonus, retirement match, healthcare costs, paid time off, commuting expenses, remote-work flexibility, and other benefits
A slightly smaller salary with significantly better benefits may still leave you ahead.
Likewise, a raise accompanied by higher insurance premiums or other costs might not feel as large as the headline number suggests.
After considering inflation and your actual expenses, did your last raise really move you forward? |
 |
Don't Confuse Appreciation With Compensation |
Getting a raise feels good.
It can feel like recognition...validation... proof that the work you're doing matters... and there's nothing wrong with appreciating that.
But you should still understand the numbers.
A 3% raise isn't automatically good or bad.
The better question is...
Did my compensation grow with the value I'm providing and with the cost of living I'm experiencing?
This is where financial awareness becomes career awareness.
If your income isn't keeping pace year after year, eventually you may need to ask...
Have my responsibilities increased? Have my skills improved? Has my market value increased? What are comparable positions paying? Is there a better opportunity somewhere else?
Last week we talked about increasing income.
This is exactly why. Sometimes waiting for annual raises isn't enough.
Loyalty to your employer shouldn't require quietly accepting a lower standard of living every year.
That doesn't mean constantly chasing another job.
It means understanding what your time, experience and skills are worth. |
 |
Give Yourself an Annual Compensation Review |
While your employer reviews your performance, you should review your compensation.
Once a year, sit down and answer these questions...
1. What percentage raise did I receive? Don't just look at the dollar amount... calculate the percentage.
2. How much did my major expenses increase? Look at housing, groceries, insurance, utilities, transportation and healthcare.
Your personal inflation rate may feel very different from a national average.
3. Did my responsibilities change? Are you doing more than you were a year ago? Managing more? Solving harder problems? Providing more value?
4. Did my skills improve? Did you earn a certification? Learn a new technology? Take on leadership responsibilities? Build experience that makes you more valuable elsewhere?
5. What is the market paying? Research comparable positions.
You don't have to leave your employer... but you should understand what your experience is worth.
6. What would I do with a larger raise? Decide before the money arrives.
Maybe... increase retirement contributions... accelerate debt payoff... increase emergency savings... invest more... enjoy some of it intentionally
A raise is an opportunity. Give it a job! |
I think this is one of those financial realities that's easy to miss.
We see the salary increase. We celebrate the percentage. And we assume we're moving forward.
But financial progress isn't simply earning more dollars. It's increasing what those dollars allow you to do.
If your paycheck goes up 3% and everything you need goes up around the same amount... You may simply be running faster to stay in the same place.
That doesn't mean you shouldn't appreciate the raise.
Take the win... But understand what the win actually means. And if year after year your income isn't keeping pace with your expenses, don't immediately assume the only answer is cutting more from your budget.
Maybe it's time to increase your value... Learn something... Ask for more... Negotiate... Explore the market... Or consider whether someone else is willing to pay more for the skills you've already built.
You can't control inflation... But you can keep working on something you have much more influence over... Your earning power.
Until next week,
Disclaimer: Guide to Perfect Credit and Credit Coach Rob provide financial education and coaching based on personal experience and research. We are not licensed financial advisors, accountants or attorneys. This content is for informational purposes only and should not be considered financial, legal or tax advice. Always consult with a certified professional for your specific situation. |
Get The 850 Pin! |
It’s more than a number... it’s a symbol of the journey. My journey started with free t-shirts and ended at 850.
What's yours?
#850Journey #CreditComeback #YouGotThis |